Can You Get Life Insurance with Type 2 Diabetes Without Taking Medication?
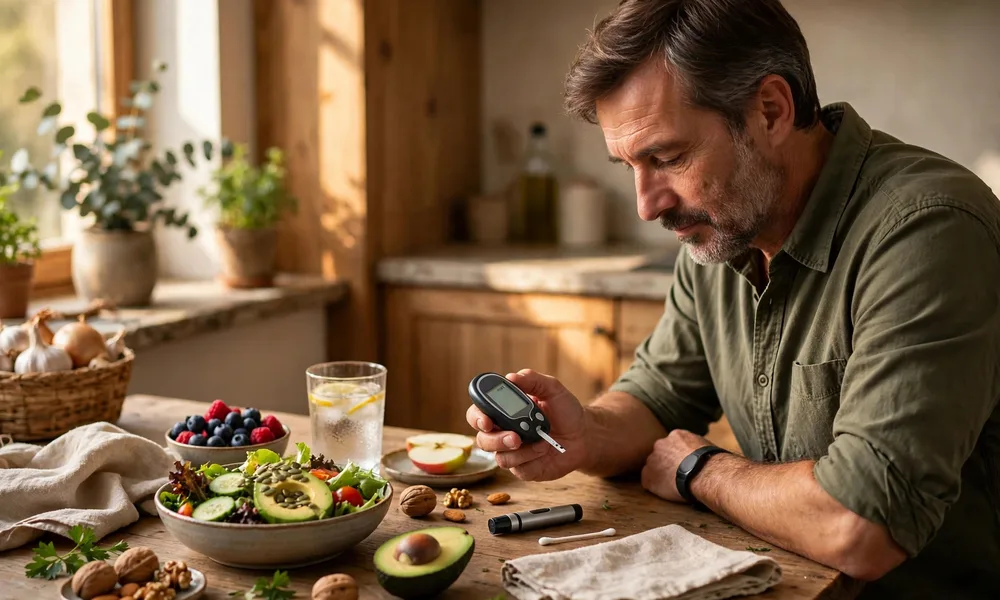
Many people with type 2 diabetes manage their blood sugar with food, activity, and weight control, without taking diabetes medication. When they apply for life insurance, they often ask the same question: does not taking medication help, hurt, or make no real difference?
This article gives general information only, not financial or medical advice. It explains how insurers usually look at type 2 diabetes, why control matters more than the medication label, and how to prepare a stronger application. It does not promise approval or any price, because no honest guide can. Please talk to your own doctor for personal decisions about your health and diabetes care.
| Quick Facts | Details |
|---|---|
| Topic | Life insurance with type 2 diabetes managed without medication |
| Category | Health |
| Short answer | Yes, people with type 2 diabetes can often apply and be considered; the outcome depends on the full health picture |
| Key measure insurers use | HbA1c, which shows average blood sugar over about two to three months |
| How insurers group management | Sources describe diet controlled cases as generally viewed more favorably than oral medication, then insulin, though each insurer differs |
| Other key factors | Age at diagnosis, complications, blood pressure, cholesterol, weight, and tobacco use |
| Important rule | Always answer application questions honestly; insurers can check medical records |
How Life Insurance Underwriting Works, in Simple Words
Life insurance underwriting is the process an insurer uses to decide whether to offer cover, and at what price. The insurer is trying to estimate risk over many years. It looks at age, health history, lifestyle, and medical records, then places the applicant into a risk class. Better risk classes usually pay less. Higher risk classes pay more, sometimes through what the industry calls a table rating, where a percentage is added to the standard price.
Diabetes does not mean an automatic no. Insurers deal with diabetes applications every day, and well controlled type 2 diabetes is one of the more common health conditions they assess. What matters most is not the word diabetes on its own. It is the detail behind it: how long you have had it, how well it is controlled, and whether it has caused other health problems.
Each insurer uses its own guidelines and its own claims experience. That means the same person, with the same test results, can get a different answer from different companies. One insurer may offer standard terms while another adds a rating or asks for more evidence. This spread is normal, and it is one reason people often compare more than one insurer, or use a broker who knows which companies handle diabetes cases well.
What Not Taking Medication Actually Tells an Insurer
Managing type 2 diabetes without medication usually means your doctor is comfortable that food, activity, and weight control are keeping your blood sugar in target range for now. To an underwriter, that can be a positive sign. Industry sources describe a general order in how management is viewed: diet controlled diabetes tends to be viewed most favorably, then diabetes managed with oral medication, then diabetes managed with insulin. That order is a pattern, not a promise, and insulin use alone does not disqualify anyone.
But underwriters do not stop at the medication question. Some application forms ask mainly whether you use insulin, rather than asking for the name of every tablet. What they study closely is your HbA1c result and its trend over time. One good reading helps. A steady record of readings in range, across regular checkups, helps more, because it shows control is stable and not a one-off.
There is another side to this. Not taking medication only helps if the numbers back it up. If a person is not on medication but their HbA1c is high, an insurer will focus on the high reading, not on the absence of tablets. And if a doctor has advised medication and a person has chosen not to take it, underwriters may see that as a concern about following medical advice. Insurers value a record of keeping appointments and following the plan agreed with your doctor.
Never stop or skip medication in order to look better on an application. That would be unsafe, and it would not fool the process anyway, because insurers look at test results and medical records, not just at a medication list.
The Main Factors Insurers Usually Assess
The first factor is blood sugar control. HbA1c is the headline number because it reflects average blood sugar over the prior two to three months. In general industry terms, lower and stable readings are viewed more favorably, and readings that show poor control make standard terms harder to get and can lead to higher ratings or a decline from some insurers. Exact cut-offs differ by company, so this article does not present any single number as a guarantee.
The second factor is age at diagnosis and time since diagnosis. Someone diagnosed later in life, with a shorter history of the condition, is often viewed differently from someone diagnosed young who has lived with diabetes for decades. A longer history means more years in which complications could develop, and underwriters take that into account.
The third factor is complications. Insurers look closely at whether diabetes has affected the eyes, such as retinopathy, the kidneys, the nerves, such as neuropathy in the feet and legs, or the heart and blood vessels. In many cases, complications weigh more heavily in the decision than the diabetes itself. A person with no complications is in a much stronger position than a person with several, even at the same HbA1c level.
The fourth factor is the rest of the health picture. Blood pressure, cholesterol, weight and body mass index, and tobacco use all matter. Smoking combined with diabetes is treated as a much higher risk. So is a mix of diabetes with heart disease or high blood pressure that is not controlled. Underwriters judge the whole picture together, not each item alone.
What the Application Process Usually Involves
Expect detailed health questions. Insurers commonly ask your age at diagnosis, how your diabetes is managed, how often you see a doctor, whether you test your blood sugar and what the results are, and whether you have had problems with your eyes, heart, kidneys, or circulation.
Many applicants with diabetes are asked for more than the form. An insurer may request a medical exam, blood and urine tests, or your recent medical records. Some may accept recent test results from your own doctor if you had a full physical with blood and urine work in the last six to twelve months, though this varies. Insurers may also check prescription history databases and the Medical Information Bureau, a shared record used in the industry.
Common Mistakes That Hurt an Application
The biggest mistake is giving wrong or incomplete answers. Always disclose your diabetes. Applications ask about it directly, insurers can check medical records when a claim is made, and cover bought with wrong answers may not pay out when your family needs it. Honesty is not just the right thing to do; it protects the policy itself.
A second mistake is applying to only one insurer and accepting the first answer as final. Because guidelines differ, a decline or a high rating from one company does not settle the matter. A third mistake is applying right after a single poor test result without context. If a reading was unusually high because of illness or a short term problem, medical records that show your normal trend can help an underwriter see the full story.
A fourth mistake is ignoring the basics you can control before you apply: keeping regular checkups, knowing your latest HbA1c, blood pressure, and cholesterol numbers, and having your records in order. You cannot change your age at diagnosis, but you can present a clean, complete, well documented case.
Finally, be careful with any person or website that promises approval, promises a set price, or tells you to hide a condition. No one can promise what an underwriter will decide. Treat such promises as a warning sign.
Who This Route Suits, and a Sensible Way Forward
Applying without diabetes medication in the picture suits people whose diabetes is genuinely well controlled through lifestyle, who have no complications, who see their doctor regularly, and whose other measures, such as blood pressure and weight, are in a healthy range. Those applicants are usually in the strongest position an insurer sees among people with type 2 diabetes, though terms still vary by company.
A sensible way forward has a few steps. First, gather your facts: diagnosis date, recent HbA1c results, other test results, and a list of any other conditions and medicines. Second, compare insurers or speak with an independent broker or adviser who handles diabetes cases often. Third, answer everything fully and honestly. Fourth, if the first offer is expensive, ask whether a different insurer or a different policy type would treat your case better, rather than giving up.
Remember that your health comes first in all of this. Keep managing your diabetes in the way your own care team advises, whether that includes medication or not. Please talk to your own doctor for personal decisions about your diabetes, and take separate regulated financial advice before choosing a policy.
You may also read: How Do Dermal Fillers Work and What Should You Expect?
FAQs
Can I get life insurance if I manage type 2 diabetes without medication?
In many cases, yes, you can apply and be considered. Diet controlled diabetes with good test results and no complications is generally viewed favorably by insurers. But no guide can promise approval or a price, because each insurer judges the full record in its own way.
Does not taking medication always mean a lower price?
No. Insurers care most about control, shown by HbA1c results and their trend, plus complications and overall health. A person on oral medication with steady, in-range results may be treated similarly to a person without medication. A person without medication but with high readings will not gain from the medication point alone.
What questions will the insurer ask about my diabetes?
Common questions cover your age at diagnosis, how the condition is managed, whether you use insulin, how often you see a doctor, your blood sugar test results, and whether you have eye, kidney, nerve, heart, or circulation problems. You may also be asked for records, an exam, or lab tests.
Should I wait for a better test result before applying?
It can help in some cases. If a new HbA1c test is due soon and your control has improved, applying with that fresher, better result may support your case. Talk it through with an adviser, and never delay care or change treatment just for an application.
Final Thoughts
Not taking medication for type 2 diabetes can be a good sign to an insurer, but it is only one part of the story. Control, shown over time, matters most, along with your age at diagnosis, any complications, and your wider health.
Go in prepared and honest. Know your numbers, keep your checkups regular, compare more than one insurer, and be wary of anyone who promises a result. Done that way, an application becomes a fair test of your real health record, and that is the best position you can put yourself in.